



 Startups
 Creative agencies
 Onchain teams
 European businesses
 AI
 Software
TL;DR: The best multi currency account is the one that opens an account for the entity you already have, shows you the all-in FX cost before money moves, and keeps your balance under your control. Altitude accepts eligible businesses incorporated in 200+ countries, charges $0 on ACH, SEPA, and stablecoin transfers, and holds balances in fully reserved stablecoins your business controls. Product availability varies by country. Mercury and Brex, by contrast, require US incorporation, Wise charges a percentage-based conversion fee from 0.33% on every transfer, and Airwallex limits entity access to around 70+ eligible countries.
You are paying a contractor in Brazil, a supplier in Germany, and a freelancer in the UK from three different platforms. Each one shows a different exchange rate, and none of them tells you the all-in cost before you click send. Meanwhile, the account you opened last year just flagged your business as high-risk because of where you incorporated.
This multi currency business account comparison evaluates providers on the criteria that matter to a founder running a borderless business: entity eligibility, all-in FX costs, transfer speeds, and control over funds. It covers Altitude, Wise Business, Airwallex, Mercury, and Brex, with limitations named where they exist. For a detailed overview of how global business accounts work, see the guide to international business accounts.
Criteria for this evaluation
What actually predicts whether an account works for you
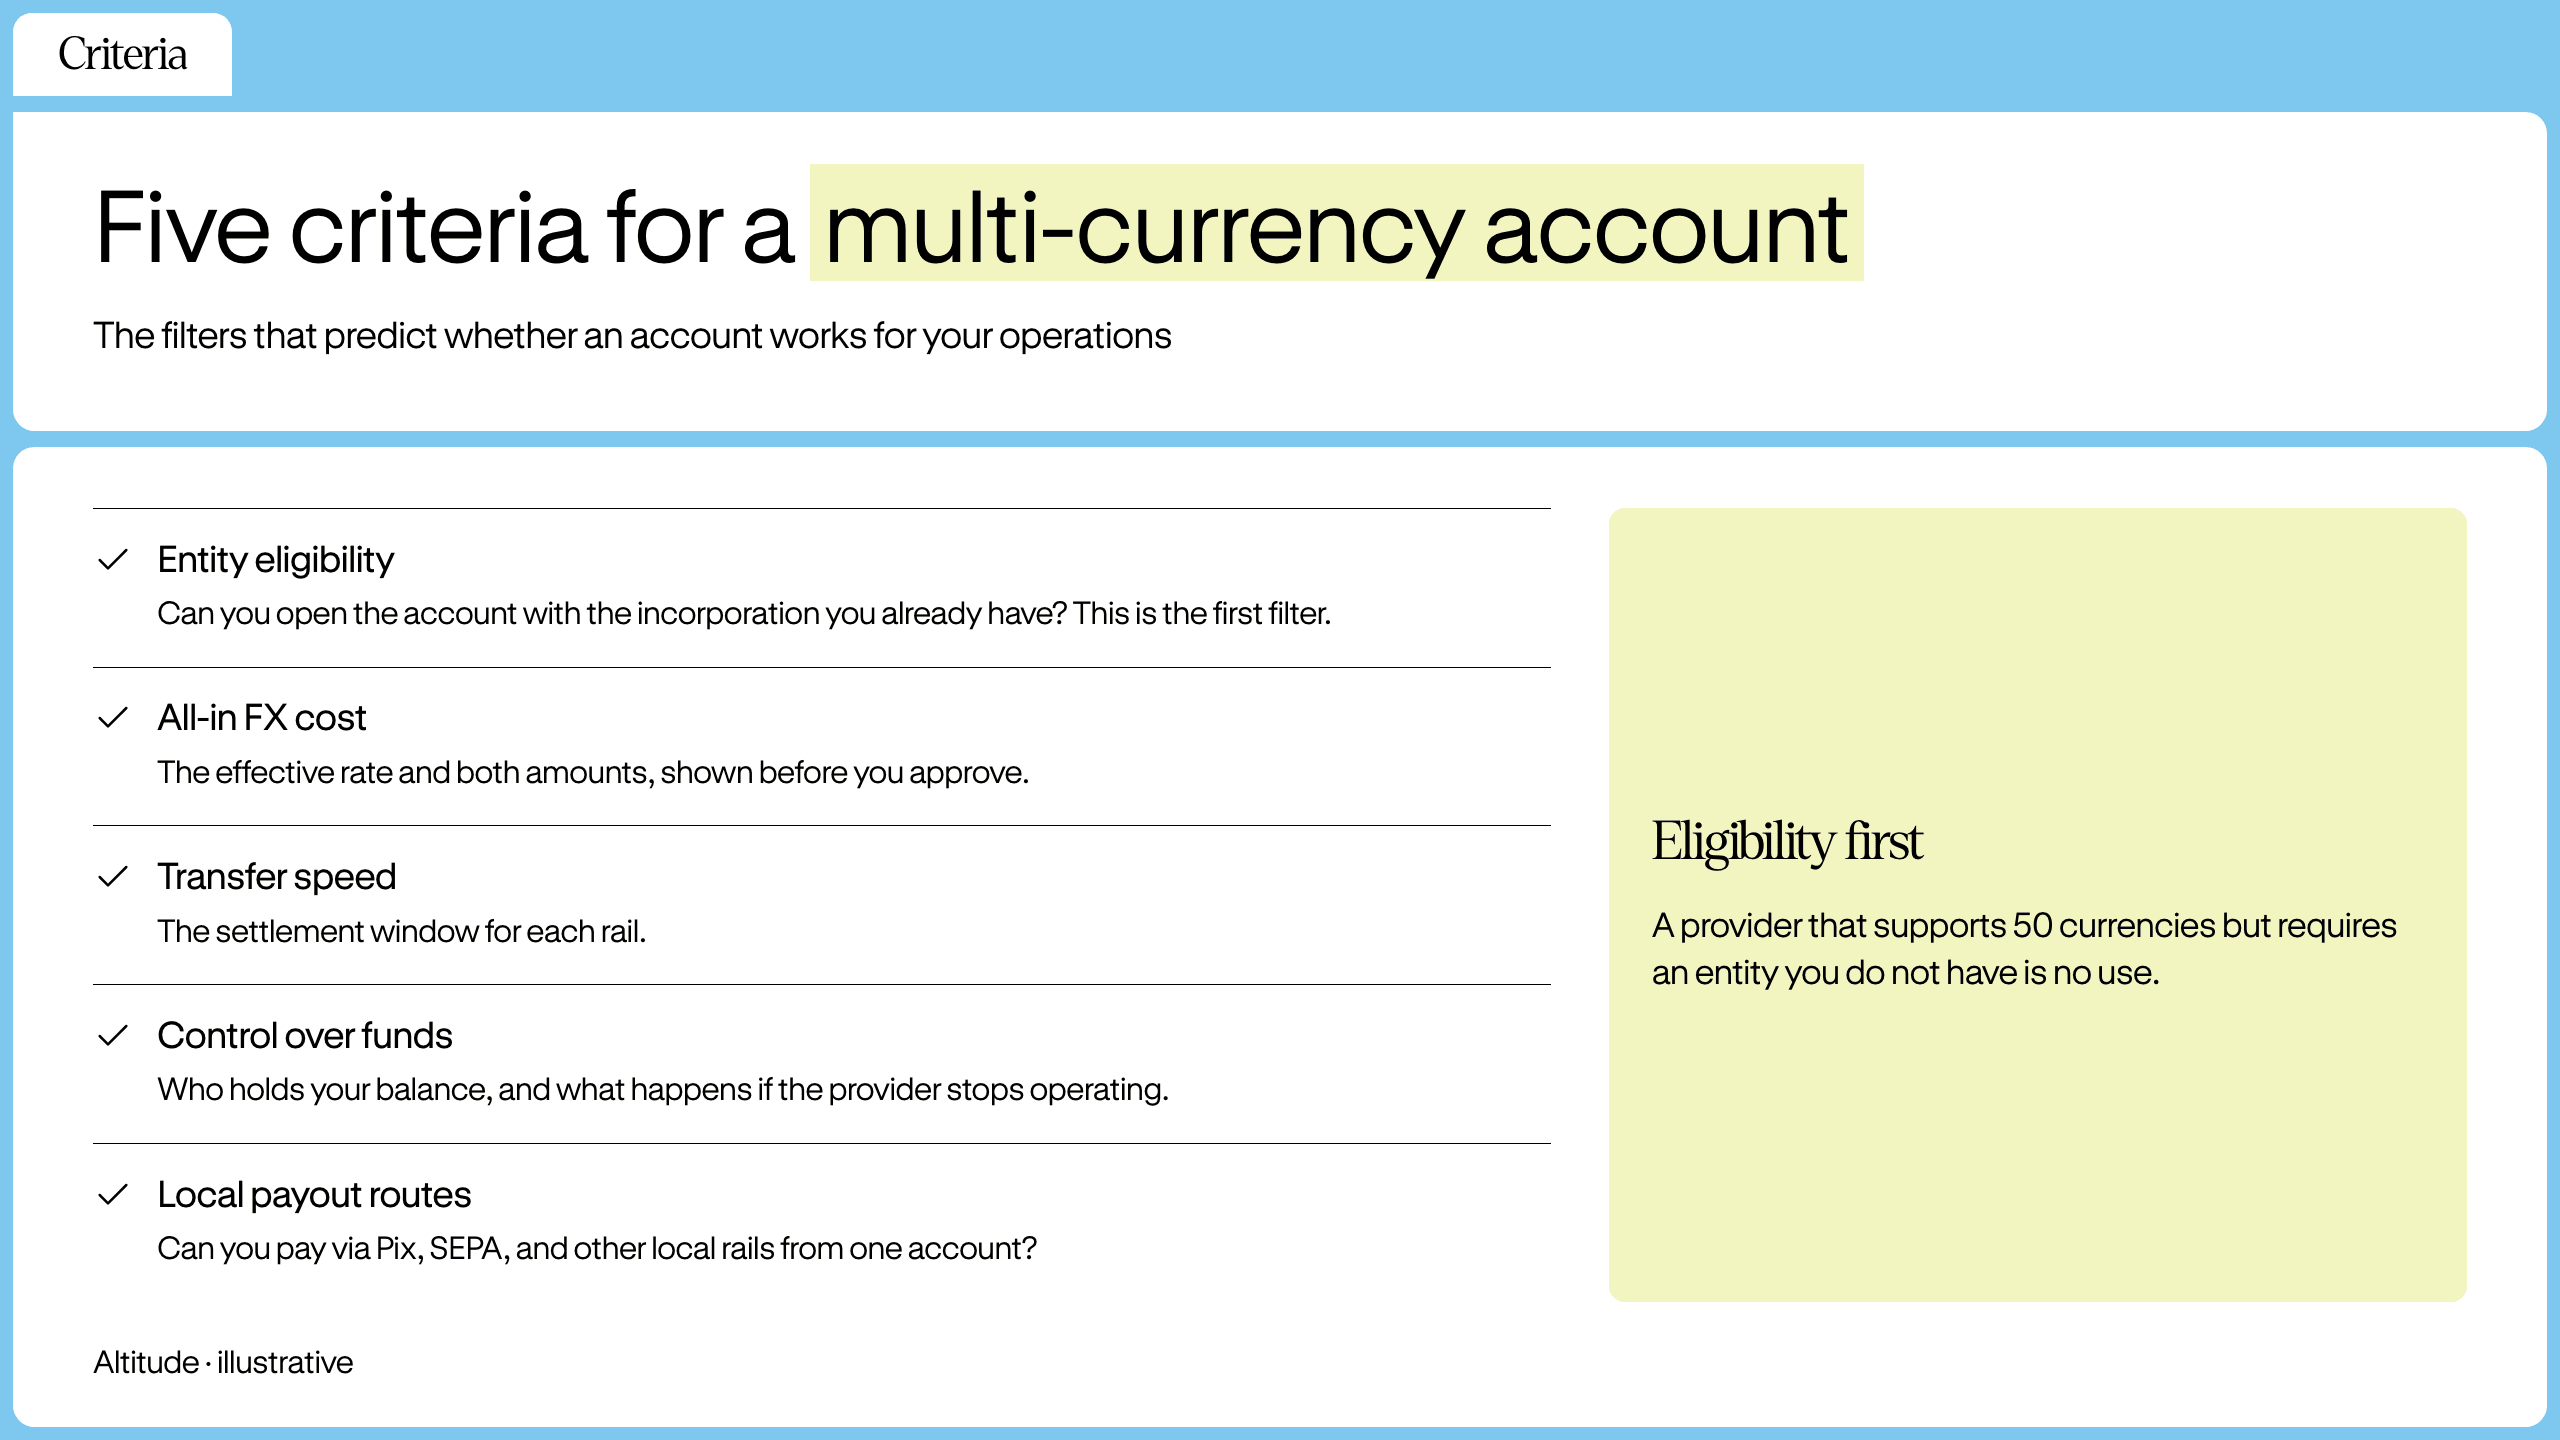
A multi currency account for business serves one purpose: getting money in and out of multiple countries without friction. The criteria that predict whether an account will work for your operations are not the ones in marketing copy.
- Entity eligibility: Can you open the account with your current incorporation? A provider that supports 50 currencies but requires a US entity you do not have is useless. This is the first filter.
- All-in FX cost: The headline fee is never the full cost. You need the effective exchange rate and both amounts (what you send, what the recipient receives) before you approve.
- Transfer speed: Settlement windows vary by rail. A payment that arrives in three days when you expected one creates reconciliation work and damages trust with contractors.
- Control over funds: Who holds your balance, and what happens if the provider stops operating? Founders who have watched peers lose access to funds without warning evaluate this before features.
- Local payout routes: Can you pay a contractor in Brazil via Pix and a supplier in Germany via SEPA from the same account? Local rails settle faster and cost less than SWIFT.
Who these accounts are built for
Multi-currency accounts are built for businesses that operate across borders by design. If you pay contractors in three or more countries, invoice customers in USD or EUR from a country where those currencies are hard to hold, or incorporated outside the US or EU, you are the target user. If your business is US-only and every transaction is in one currency, a domestic account will serve you better.
Comparing the top multi-currency accounts
Available currencies and payout reach
The number of currencies you can hold matters less than the number of places you can pay. A provider that holds 40 currencies but pays out only via SWIFT is slower and more expensive than one that holds two currencies and pays via local rails.
| Provider | Holdable currencies | Payout reach | Entity access |
|---|---|---|---|
| Altitude | USD, EUR | GBP, MXN, BRL, COP | [200+ countries](https://support.altitude.xyz/en/articles/12401045-supported-countries), no US entity required. Product availability varies by country |
| Wise Business | 40+ | Send to 160+ countries | US, UK, EEA, Canada, Switzerland, Australia, NZ, Singapore |
| Airwallex | 20+ | 200+ countries/regions (local and SWIFT) | ~69 countries incl. BVI, Cayman Islands |
| Mercury | USD only | US domestic only | US or US territory required |
| Brex | USD only | 40+ local currencies | US incorporation, EIN, US operations required |
Altitude holds USD and EUR balances in USDC and EURC (a US dollar stablecoin and a euro stablecoin) and converts to local currency at the point of payment. You cannot hold GBP, MXN, BRL, or COP as a balance. Local payout routes convert from your USD or EUR balance when you send, using Faster Payments for GBP transfers, SPEI for MXN, Pix for BRL payments, and Bre-B for COP. The recipient gets paid in local currency directly to their bank account.
Wise Business lets you hold 40+ currencies, which helps if you have recurring revenue or expenses in those currencies and want to avoid converting twice, while Altitude converts from USD or EUR at the point of payment and onboards businesses incorporated in 200+ countries. Airwallex supports 20+ holdable currencies and multi-entity management for enterprise buyers, and Altitude covers the same payment corridors from a single-entity account structure with role-based approval controls built in. Mercury and Brex hold USD only and do not support local payout routes outside the US.
FX fees and conversion rates compared
The cost of a cross-border payment is the combination of the transfer fee, the FX margin, and any intermediary bank charges. Providers that advertise "no fees" often hide the cost in the exchange rate.
| Provider | Rail | Transfer fee | FX margin |
|---|---|---|---|
| Altitude | ACH, SEPA, US wire, stablecoin | $0 | Rate shown before approval |
| Altitude | SWIFT | $35 Altitude fee (OUR convention) | Rate shown before approval |
| Wise Business | USD to BRL | Fee from 0.33% + small fixed fee (varies by corridor) | Mid-market rate |
| Wise Business | USD to GBP | Fee from 0.33% + small fixed fee (varies by corridor) | Mid-market rate |
| Airwallex | Major currencies (USD, GBP, EUR) | $0 | 0.5% above interbank |
| Airwallex | Other currencies (BRL, MXN) | $0 | 1.0% above interbank |
Wise charges a percentage-based conversion fee starting from 0.33% plus a small fixed fee that varies by corridor, rather than a fixed FX margin. Airwallex charges 0.5% above interbank on major currencies such as USD, GBP, and EUR, and 1.0% on all other currencies, including BRL and MXN, with no additional transfer fee on local rails.
Altitude shows you the effective exchange rate and both amounts before you approve. The quote refreshes every 30 seconds. You fix either "You send" or "Recipient receives," and Altitude calculates the other side.
Altitude's fee structure:
- ACH, same-day ACH, US domestic wire, and EURC-funded SEPA: $0 Altitude fee
- SWIFT outbound: $35 Altitude fee (OUR convention, you cover the known fee), with a $100 minimum per transfer. Some intermediary banks may still deduct additional charges, so full-value receipt isn't guaranteed.
- Supported stablecoin transfers: $0 Altitude fee, network fees included
For recurring payments, the FX margin compounds. A 1% margin on a $5,000 monthly contractor payment costs $600 per year. Over a team of ten contractors, that is $6,000 per year in costs that never appear on a fee schedule.
Transfer speeds and settlement windows
Settlement time depends on the rail, not the provider's marketing.
| Rail | Settlement time | Minimum transfer |
|---|---|---|
| ACH | Up to 3 business days | Varies |
| Same-day ACH | Same business day | Varies |
| US domestic wire | Typically 1 business day | Varies |
| SEPA | Typically 1 business day | Varies |
| SWIFT | Up to 5 business days | $100 |
| Stablecoin (Solana) | Minutes | Varies |
Altitude supports all six settlement methods, giving you the fastest available route for each corridor. Altitude's SEPA payments typically settle within one business day. SWIFT transfers take up to 5 business days, and the $35 Altitude SWIFT fee (OUR convention) means you cover the known fee upfront. Stablecoin transfers settle in minutes because the network does not observe banking cut-off times.
Stablecoin transfers keep money moving when bank transfer windows are closed. A contractor invoice that arrives Friday afternoon can be paid the same day if the recipient accepts USDC or EURC, rather than waiting until Monday's SEPA window.
Opening an account by entity type
The provider that will open an account for your entity is the only provider that matters. Feature lists are irrelevant if you cannot get past onboarding.
| Provider | US entity required | EU/EEA entity | Offshore jurisdictions |
|---|---|---|---|
| Altitude | No | Not stated | 200+ countries, product availability varies by country |
| Wise Business | No | Yes | Limited (country-specific) |
| Airwallex | No | Yes | ~70 countries |
| Mercury | Yes | No | No, US or US-territory incorporation required |
| Brex | Yes | No | No |
Mercury requires US company formation in the United States or a US territory. Brex requires US incorporation, EIN, and operations plus a US address (EIN stands for Employer Identification Number, the US federal tax ID issued to a business). Wise Business accepts businesses in the US, UK, EEA, Canada, Switzerland, Australia, New Zealand, and Singapore. Airwallex processes applications from businesses registered in about 69 eligible countries, including the British Virgin Islands and Cayman Islands.
Altitude opens accounts for eligible businesses from 200+ countries, with no US entity required. Product availability varies by country, and every business goes through verification. Eligibility is assessed across multiple separate scopes, which can include business incorporation, USD and EUR accounts, payment destinations, card issuance, card merchant spending, and rewards. Access to one scope does not automatically extend to others, as eligibility can be limited based on jurisdiction, account status, and other criteria.
How Altitude handles multi-currency operations
Who should choose Altitude
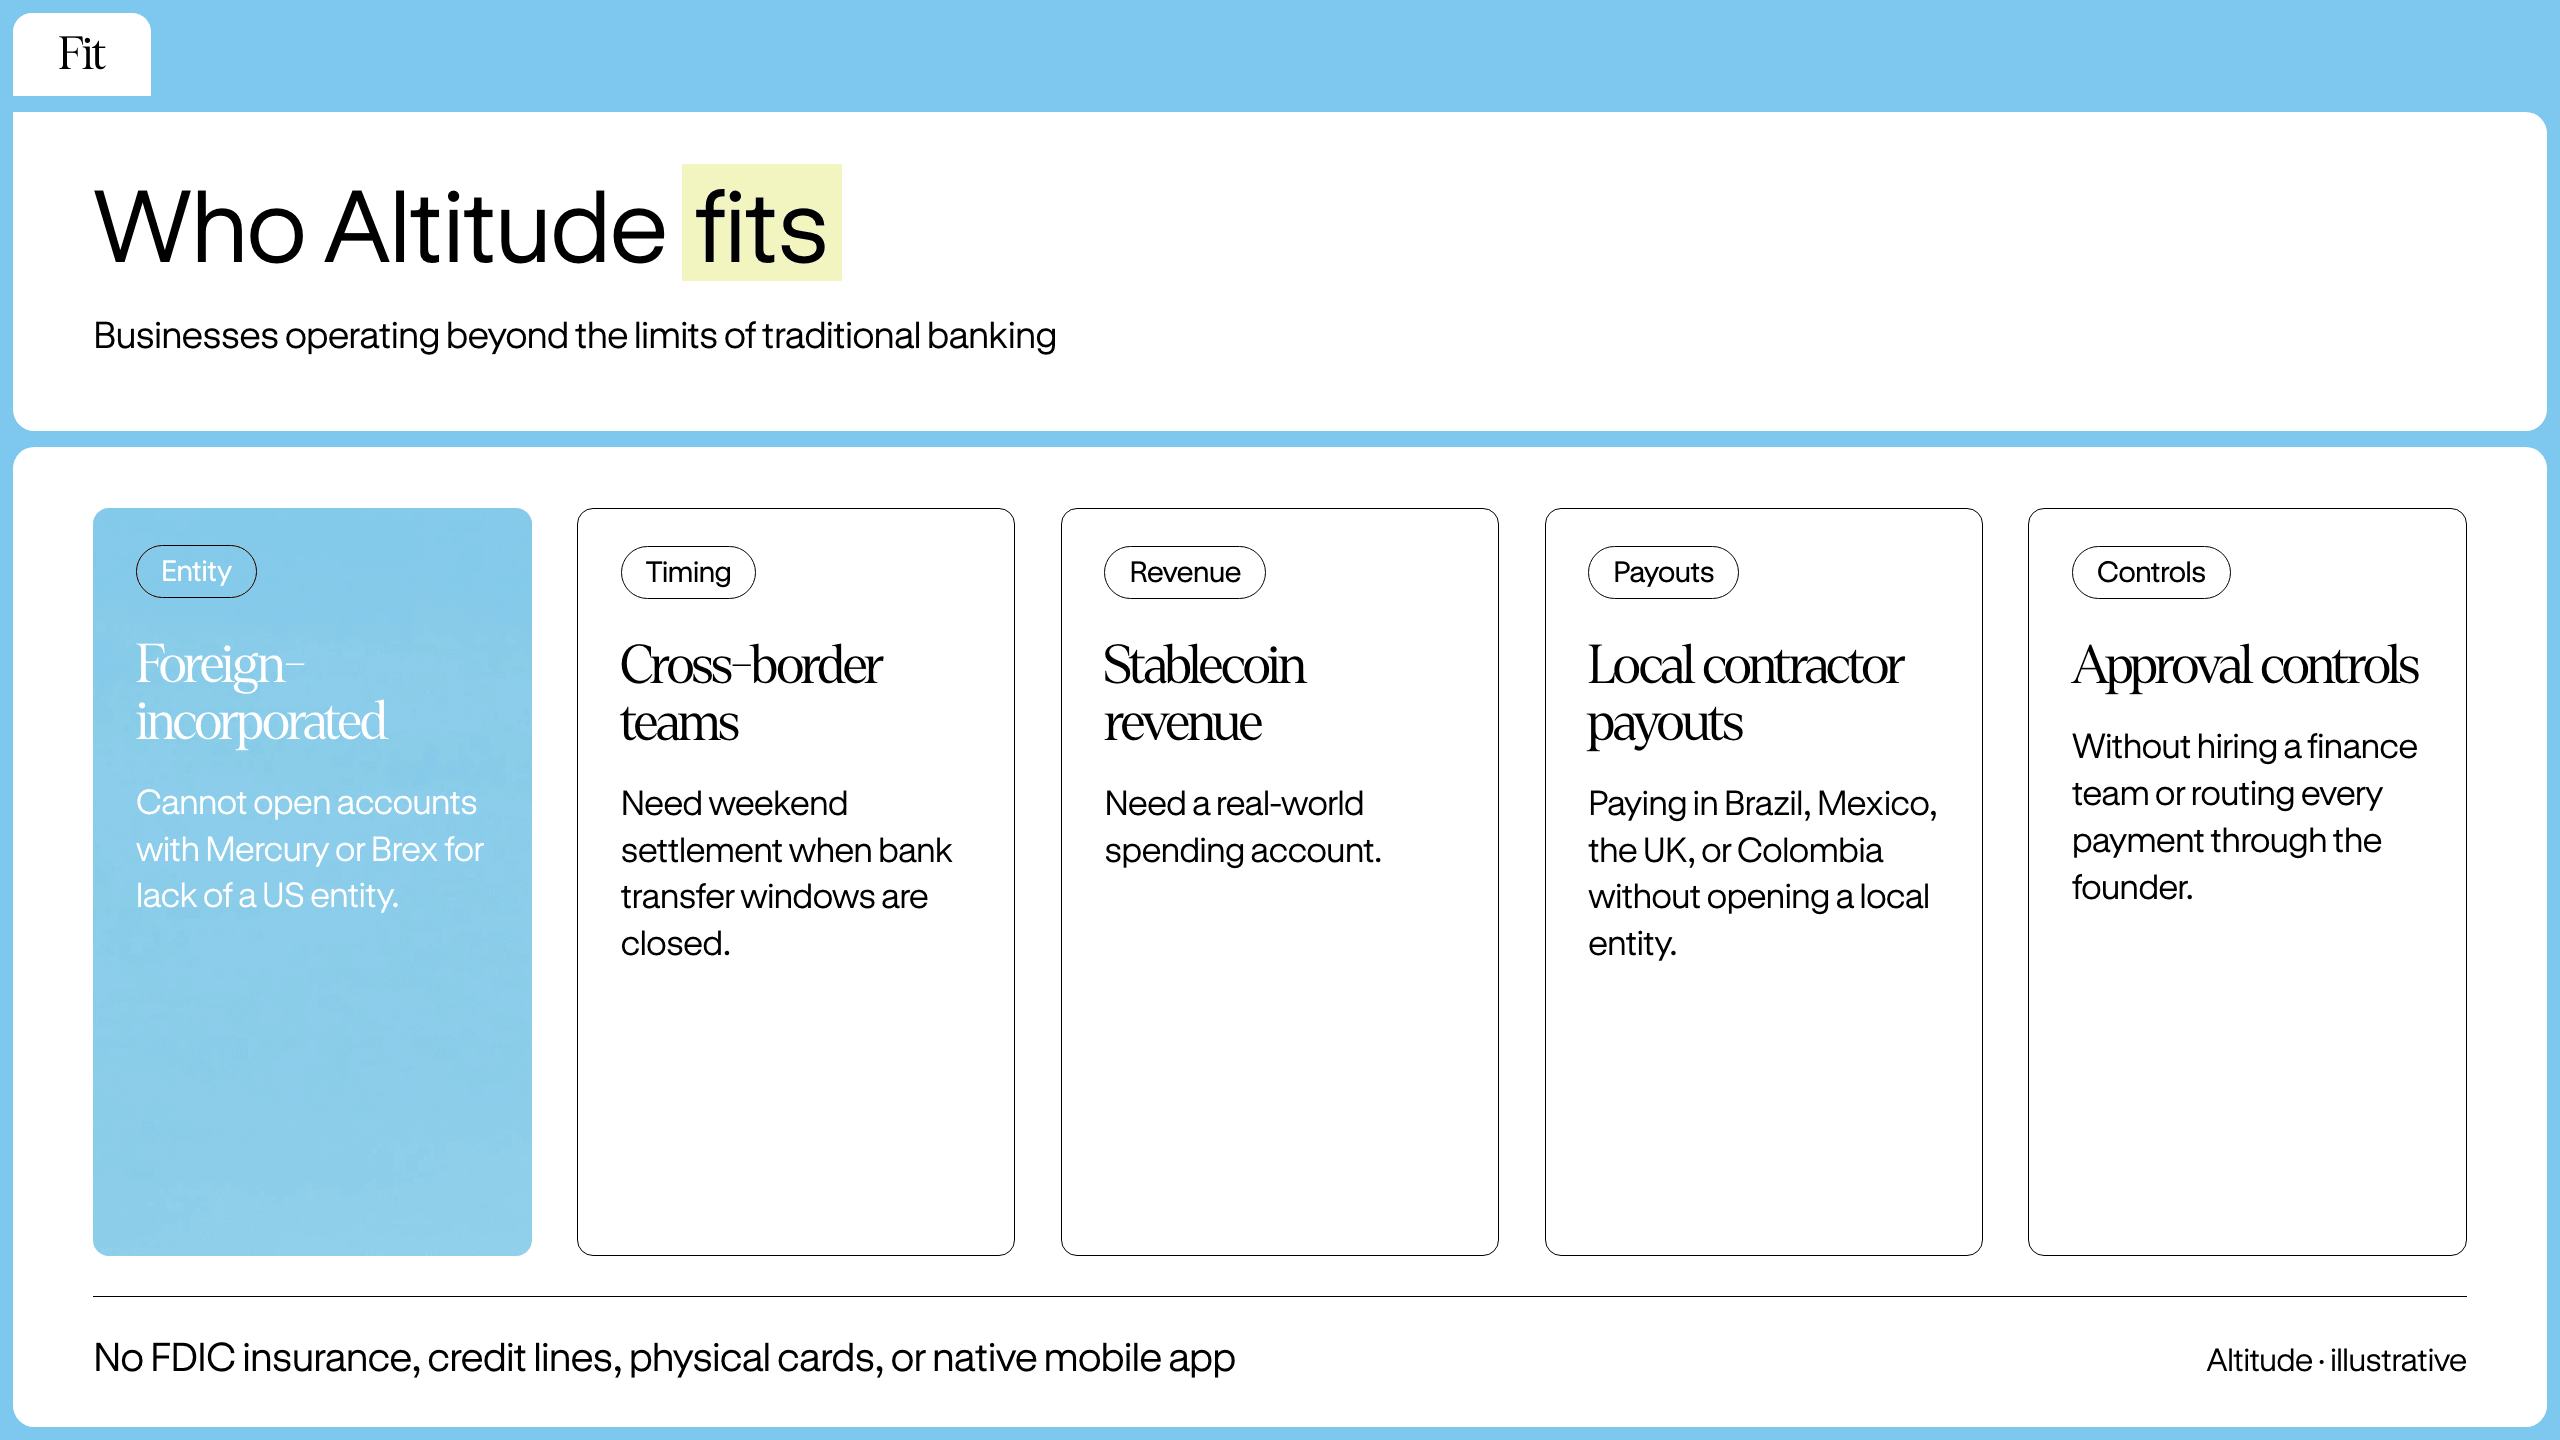
Altitude serves businesses that operate beyond the limits of traditional banking. The fit:
- Foreign-incorporated companies that cannot open accounts with Mercury or Brex because they lack a US entity.
- Cross-border teams that need weekend settlement on stablecoin transfers when bank transfer windows are closed.
- Companies with stablecoin revenue that need a real-world spending account.
- Businesses paying contractors in Brazil, Mexico, the UK, or Colombia via Pix, SPEI, Faster Payments, and Bre-B without opening a local entity.
- Teams that want approval controls without hiring a finance team or routing every payment through the founder.
Altitude does not offer FDIC insurance on operating balances because balances are held in fully reserved stablecoins, not bank deposits, and carry no deposit insurance. Altitude also does not offer credit lines, physical cards, or a native mobile app.
Currency holdings and FX costs
Altitude holds USD and EUR balances in USDC and EURC, a US dollar stablecoin and a euro stablecoin, backed one to one by the issuer's reserves, controlled by your business and not lent out by Altitude. Licensed partners, including Bridge, Rain, Infinite, and MoonPay, provide the banking services. You can create sub-accounts by team, region, or function, each with its own deposit details.
Fee structure:
- The fee structure is the same as described in the FX fees section above: $0 for ACH, same-day ACH, US domestic wire, EURC-funded SEPA, and supported stablecoin transfers.
- Outbound SWIFT: $35 Altitude fee (OUR convention), with a $100 minimum per transfer. See fee table above.
Approval controls and team access
Altitude supports role-based permissions and configurable approval thresholds at the account level. A payment above the threshold requires approval from a designated approver. A payment below the threshold can be submitted directly by the person initiating it. Your rules are applied automatically, every time, so the founder stops being the manual bottleneck for every edge case at 2am.
A payment above the threshold requires approval from a designated approver before it can be submitted.
Accounting sync and bookkeeping
Altitude syncs transactions to QuickBooks Online (QBO) and Xero. Confirm coverage for your payment mix before you rely on the sync at month-end.
Scale and payment volume
Altitude launched publicly in December 2025 and had processed $200 million in payments by its April 2026 funding round, and reported a $1 billion+ annualised run rate in payment volume across banking rails and stablecoin transfers as of 13 July 2026, with a large share from on- and off-ramp flow. The 63 customer countries of origin (as of 28 July 2026) reflect businesses using Altitude, not eligibility or coverage.
How to choose the right multi-currency account
Verify currency coverage by region
Check the provider's local payout routes for the countries where you actually pay people:
- Brazil: confirm Pix support
- Germany: confirm SEPA
- UK: confirm Faster Payments
Local routes settle faster and cost less than SWIFT on every corridor.
Calculate all-in FX fees before comparing
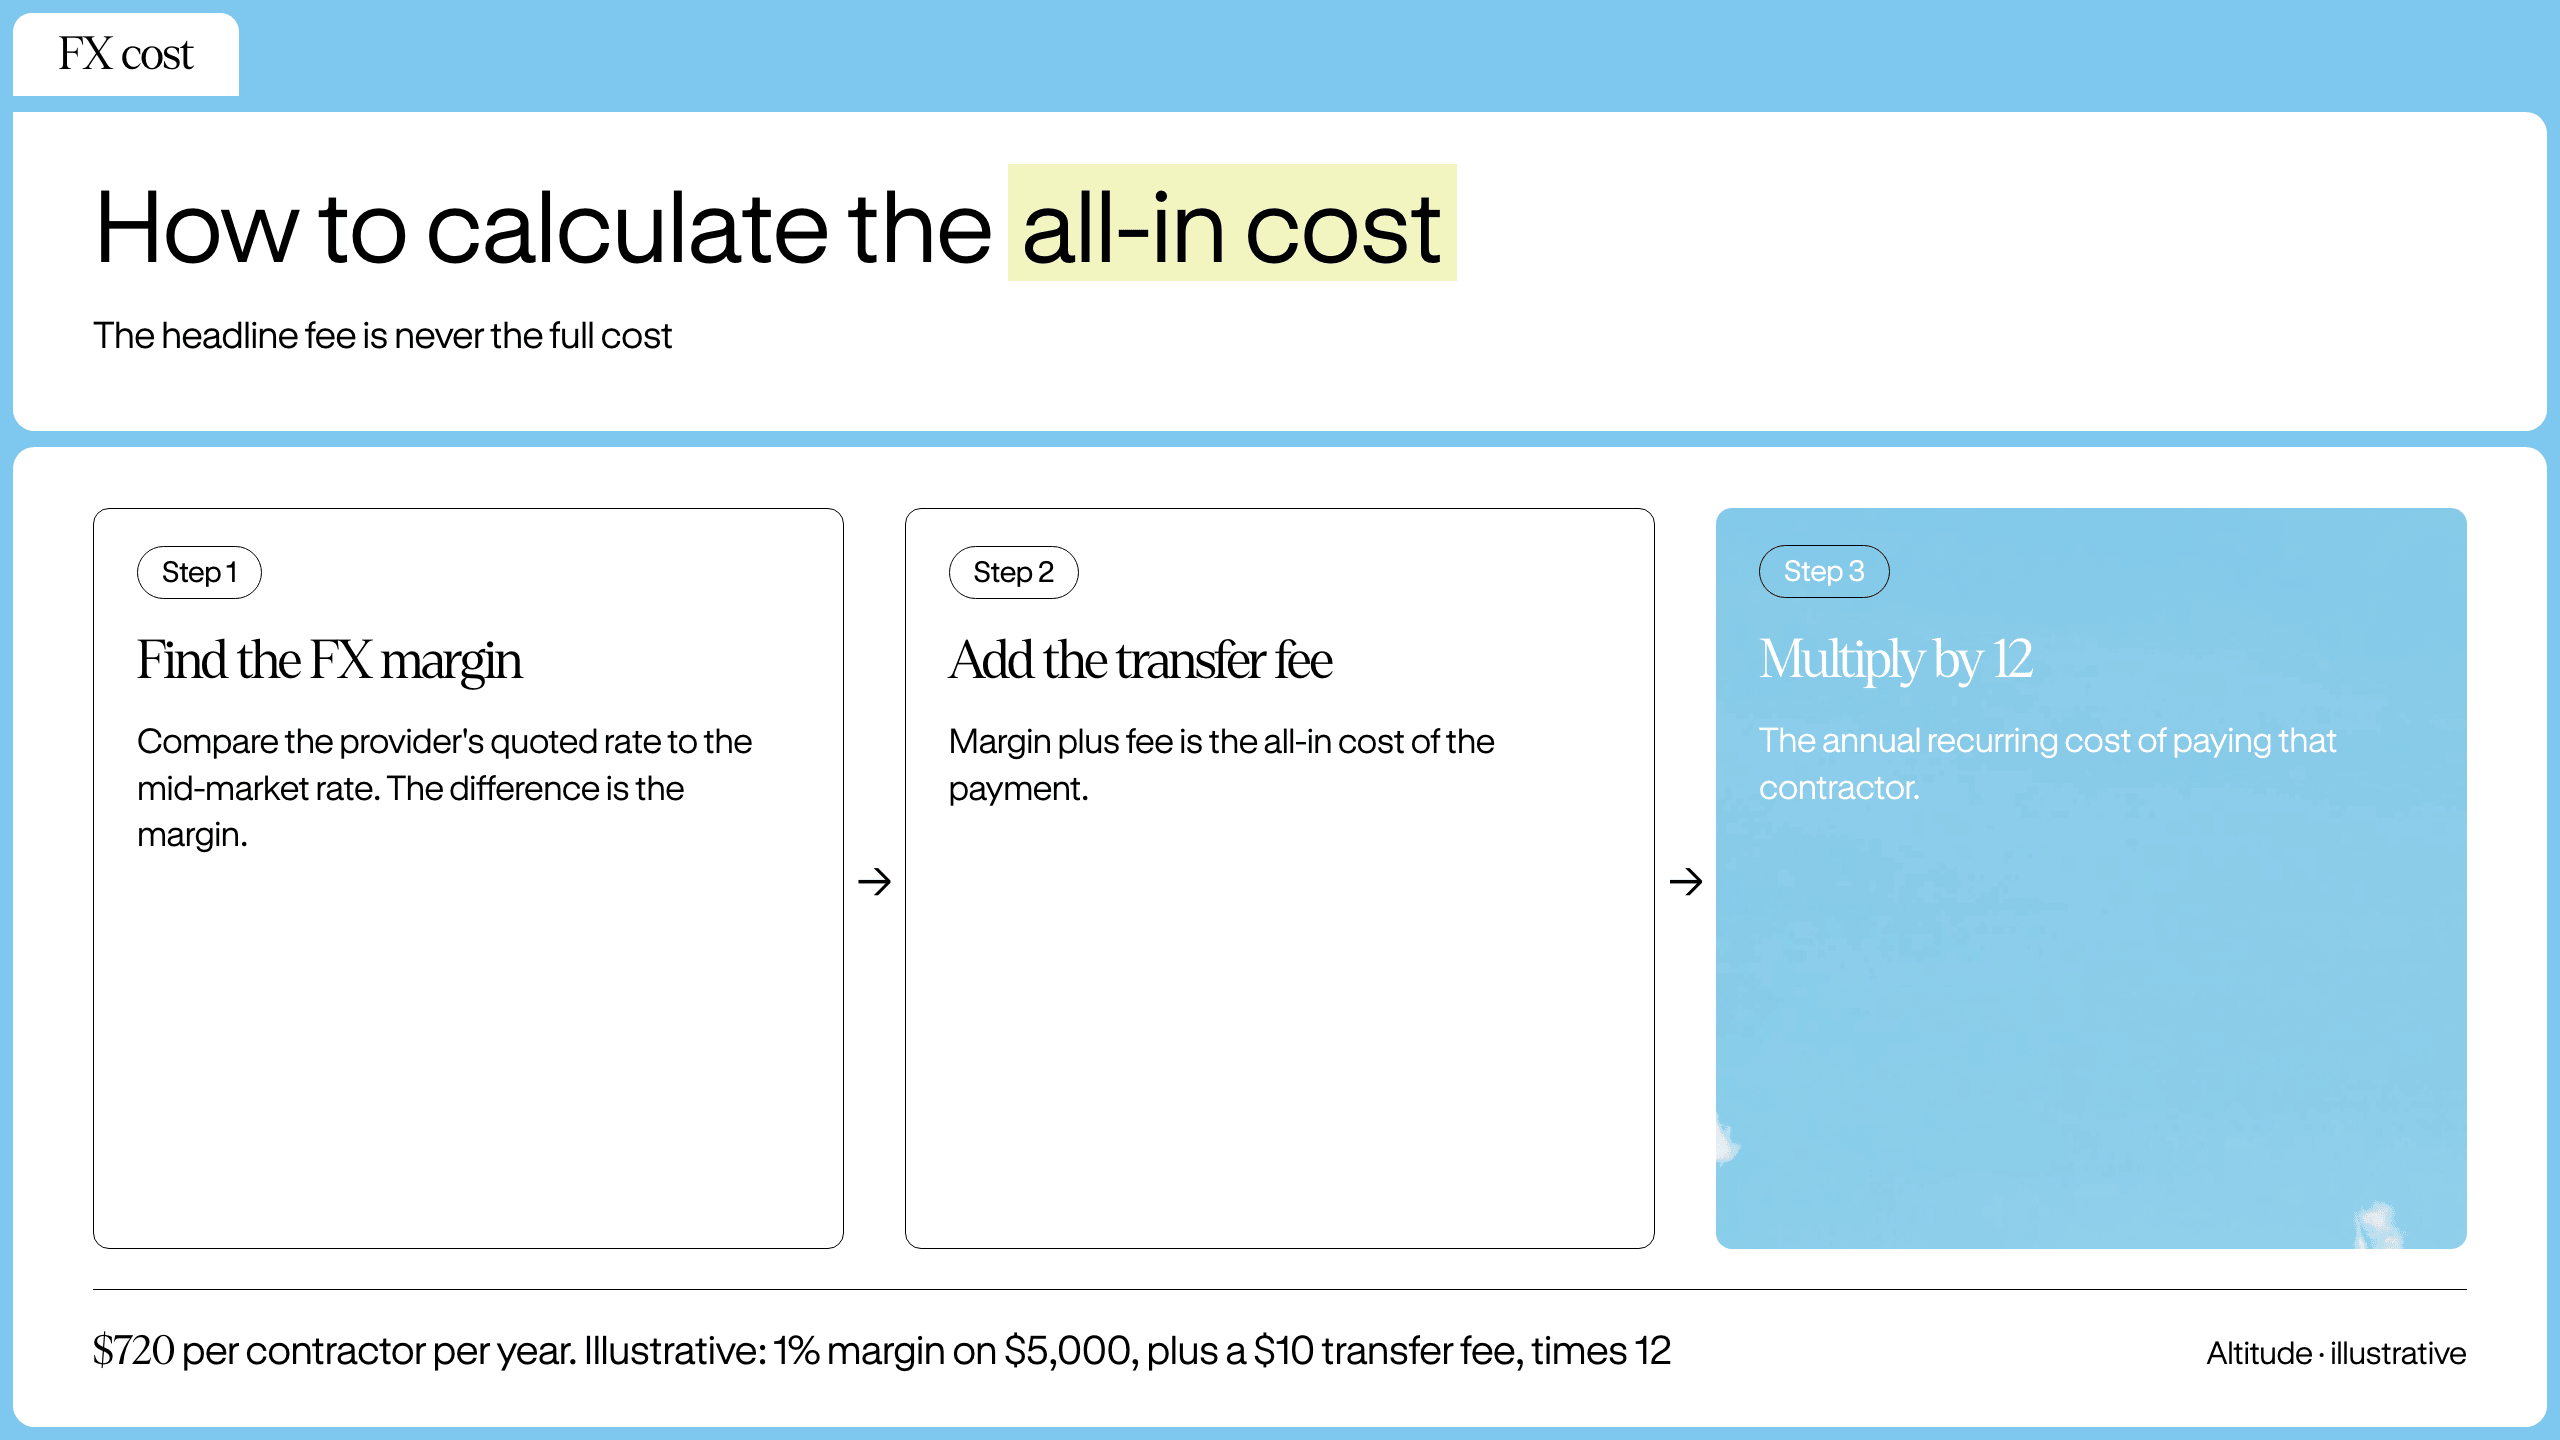
- Compare the provider's quoted rate to the mid-market rate (the rate on Google or XE). The difference is the FX margin.
- Add the transfer fee. That is the all-in cost.
- Multiply by 12 for annual recurring cost per contractor.
Example: A 1% FX margin on a $5,000 payment costs $50. Add a $10 transfer fee for $60 all-in. Over a year of monthly payments, that is $720 per contractor.
Confirm entity eligibility first
Check the provider's eligibility requirements before you start the application. Mercury and Brex require US incorporation, and Wise Business accepts businesses only in the EEA, Canada, the US, the UK, Switzerland, Australia, New Zealand, and Singapore, while Altitude accepts eligible businesses incorporated in 200+ countries. If the provider requires an entity you do not have, move on.
Test team access before committing
As your team grows, you need approval controls that work across time zones. Check the provider's role-based permissions and approval thresholds before you onboard. Check whether the provider charges per user or per workspace. For how Altitude handles multi-entity access, see the multi-entity access guide.
See how Altitude handles contractor and supplier payments across borders. Book a demo.
FAQs
What is the best multi currency account for business?
The best multi currency account is the one that opens an account for the entity you already have, shows you the all-in FX cost before money moves, and keeps your balance under your control. For founders incorporated outside the US, Altitude covers 200+ countries, so the entity you already have is likely to be eligible.
Can I hold multiple currencies in one account?
It depends on the provider. Altitude holds USD and EUR only, converting to local currency at the point of payment. Wise Business holds 40+ currencies. Airwallex holds 20+. Mercury and Brex hold USD only.
How much do multi-currency accounts cost?
Altitude charges $0 to open, $0 monthly, $0 for ACH, SEPA, and stablecoin transfers, $35 Altitude fee for outbound SWIFT (OUR convention, with a $100 minimum per transfer), and 1% on non-USD card purchases. Wise charges a percentage-based conversion fee from 0.33% plus a small fixed fee that varies by corridor. Airwallex charges 0.5% above interbank on major currencies and 1.0% on others, with no additional fee on local rails.
Do I need a US or EU entity to open an account?
Not with every provider. Altitude opens accounts from 200+ countries with no US entity required. Mercury and Brex require US incorporation. Wise and Airwallex accept a range of countries but restrict eligibility by jurisdiction.
How long do international transfers take?
ACH takes up to 3 business days. SEPA typically settles within 1 business day. SWIFT takes up to 5 business days. Stablecoin transfers settle in minutes on Solana, which settles around the clock without banking cut-off times. Settlement depends on the rail, not the provider's marketing.
Key terms glossary
Payment rail: The network a payment travels on. Examples: ACH, SEPA, SWIFT, Faster Payments, Pix, SPEI. Each rail has its own settlement time, fee structure, and geographic coverage.
FX margin: The difference between the exchange rate a provider quotes and the mid-market rate. A 1% margin on a $5,000 payment costs $50. Margins compound on recurring payments.
Local payout route: A payment method that settles in the recipient's local currency via a local payment system, such as Pix in Brazil or SPEI in Mexico. Local routes settle faster and cost less than SWIFT.
Entity eligibility: The requirement that your business be incorporated in a specific country to open an account. Mercury and Brex require US incorporation, Altitude does not.
Approval threshold: A configurable rule requiring payments above a set amount to be approved before execution. Payments below the threshold can be submitted directly.
Settlement window: The time from payment initiation to arrival in the recipient's account. ACH takes up to 3 business days. Stablecoin transfers settle in minutes.
Fully reserved stablecoins: Digital dollars and euros backed one to one by the issuer's reserves. Altitude holds balances in USDC (a US dollar stablecoin) and EURC (a euro stablecoin), controlled by your business and not lent out by Altitude.
Altitude is a financial technology platform, not a bank or digital asset custodian.